Aquafinancial Consulting
  • HOME
  • SERVICES
    • INDIVIDUALS & FAMILIES
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING FOR YOUNG FAMILIES
      • ESTATE PLANNING FOR RETIREES & MATURE FAMILIES
      • INSURANCE PLANNING
    • BUSINESS OWNERS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
      • SUCCESSION PLANNING
      • INSURANCE PLANNING
    • INCORPORATED PROFESSIONALS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
    • INSURANCE
      • DISABILITY
      • CRITICAL ILLNESS
      • LIFE
        • PERSONAL
        • CORPORATE
      • HEALTH & DENTAL
      • FOR YOUNG FAMILIES
      • FOR BUSINESS OWNERS
    • INVESTMENT
      • REGISTERED EDUCATION SAVINGS PLAN
      • TAX FREE SAVINGS ACCOUNT
      • REGISTERED RETIREMENT SAVINGS PLAN
      • REGISTERED RETIREMENT INCOME FUND
      • ANNUITIES
    • GROUP BENEFITS
      • HEALTH BENEFITS
      • RETIREMENT BENEFITS
  • ABOUT
    • ABOUT
    • SUPPLIERS
    • PRIVACY & WEBSITE TERMS OF USE
  • NEWS
  • EVENTS
  • CONTACT
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to LinkedIn
  • Link to Facebook
  • Link to X

Archive for category: Insurance

The Benefits of Working With An Employee Benefits Specialist

September 2, 2026/in Blog, Business owners, Corporate, dental benefits, group benefits, Health benefits, Insurance/by Aquafinancial Consulting

We understand that when looking for employee benefits, you’re looking to do so cost-effectively. But it’s essential to make sure you work with an employee benefits specialist, no matter what the price tag is on your benefits package. 

We’ll explain how an employee benefits specialist differs from a generalist and why working with an employee benefits specialist is so important.

How does an employee benefits specialist differ from a generalist?

You may have approached financial advisors who can handle various tasks, such as selling you insurance products, investments, and employee benefits. However, this kind of financial advisor would be considered a generalist, and they lack in-depth knowledge of how complex employee benefits can be.

An employee benefits specialist is the opposite of a generalist. They are licensed advisors who have dedicated their practice to employee benefits. Employee benefits specialist prides themselves on understanding all the nuances associated with employee benefits. A specialist undergoes further training and acquires in-depth knowledge about employee benefits. 

Why is it essential to work with an employee benefits specialist?

Employee benefits plans are complex, and your business could be at risk if your employee benefits program isn’t administered correctly. As you know, employee benefits form a part of an employee’s compensation package. 

These are the benefits of working with an employee benefits specialist:

  • We help provide the best employee benefits suited for you and your business. 

  • We provide a smooth employee enrollment program so your employee saves time. 

  • We help your employees with questions about their employee benefits program. 

  • We educate your employees about how the benefits program works for them. 

  • We know how to deal with complicated benefits claims. 

  • We can explain how to reduce the risk of any liabilities associated with offering employee benefits programs—for example, offering mandatory enrollment versus voluntary enrollment in a benefits program. You can run into issues with voluntary enrollment if your enrollment level is below the required threshold.

  • We can explain how your benefits program can work for different employment situations, such as seasonal and contract workers.

The bottom line is that working with an employee benefits specialist means you’ll have access to a well-designed and administered benefits plan. 

How can I get started working with an employee benefits specialist?

Ready to make a move to working with an employee benefits specialist? We’re here to help you get the benefits program to attract and retain employees. Call us today to get started!

Contact us

https://aquafinancialconsulting.com/wp-content/uploads/2026/09/The-Benefits-of-Working-With-An-Employee-Benefits-Specialist.jpg 250 500 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2026-09-02 16:10:302026-09-02 16:10:38The Benefits of Working With An Employee Benefits Specialist

Financial Checklist for New Parents in Canada

June 30, 2026/in Blog, Insurance, Investment/by Aquafinancial Consulting

What to Do Financially When You Have a Baby

A new baby brings a lot of joy, and a lot of new to-do lists. Most of them are about feeding schedules and car seats. But a few items on the list are about money, and they matter more than you might think.

You do not need to do everything at once. A newborn keeps you busy enough. The steps below can be spread out over the first few months. Think of this as a simple checklist you can come back to as you find the time and energy.

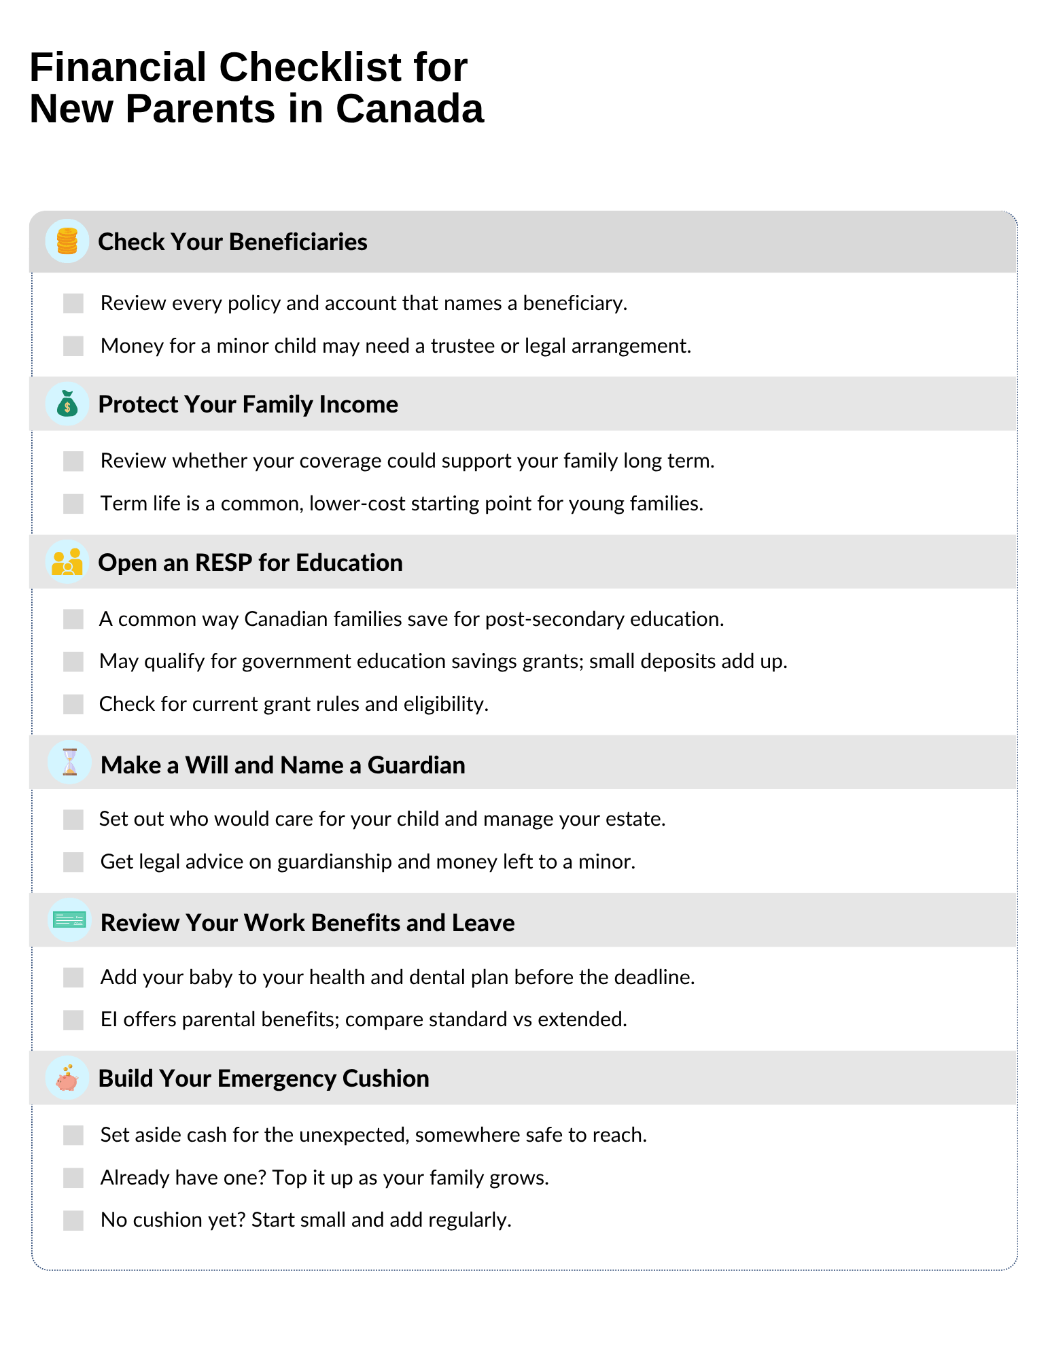
Check Your Beneficiaries

A beneficiary is the person who receives the money from your life insurance or certain registered accounts after you pass away. Many people set these up years ago and never look at them again.

Now is a good time to check. You may want to add your partner, update an older choice, or think through how money should be handled for your child. If you want money to go to a minor child, it may need to be managed through a trustee or other legal arrangement until the child is of age, depending on the asset and the province.

The key point is simple. Look at every policy and account that names a beneficiary, and make sure the names and instructions still match the life you have today.

Protect Your Family Income With Life Insurance

When it was just you, or just you and your partner, a gap in income may have been easier to manage. With a baby who depends on you, the stakes are higher. Life insurance can help protect your family financially if something happens to you, so they can keep up with housing costs, bills, and daily expenses.

For many young families, term life insurance is a common starting point. It covers you for a set number of years, often when your children are young and your financial obligations are highest. The premiums are usually lower than permanent coverage, which can make it easier to fit into a new-parent budget.

Your need for coverage often increases when you have a child. It is worth checking whether your current coverage, including any through work, would be enough to support your family for more than just the short term.

brandableContent

Open an RESP for Education

A Registered Education Savings Plan, or RESP, is a common way Canadian families save for a child’s post-secondary education. One reason many parents use it is the government support that can come with it through education savings grants.

You do not need a large amount to begin. Even small, regular deposits can add up over time. Check canada.ca for the current grant rules, contribution details, and eligibility requirements.

Make a Will and Name a Guardian

This is the step many new parents put off, and it is one of the most important. A will helps set out who would care for your child and how your estate should be handled if you and your partner die.

For parents, the most important part is often naming the person you want to care for your child. In BC, a will can express your wishes about guardianship, but it is also important to work with proper legal advice so your will deals clearly with both the care of your child and the management of any money left to a minor.

If you already have a will, a new baby is a good reason to review it. Add your child, confirm your choices, and make sure your estate plan still reflects your wishes.

Review Your Work Benefits and Leave

Your job may offer more help than you realize. Many group benefit plans allow you to add a new dependent, but the deadline depends on the plan. Check with your human resources team or plan administrator as soon as possible after the birth so you do not miss the deadline for health and dental coverage.

Employment Insurance, or EI, also offers maternity and parental benefits for eligible parents. Parents can choose standard or extended parental benefits, and the timing and number of weeks differ between the two options, so it is important to review the current rules before applying.

Build Your Emergency Cushion

A baby comes with surprises, and some of them cost money. An emergency cushion is simply cash set aside for the unexpected, kept somewhere safe and easy to reach.

If you already have one, this is a good time to top it up. A larger family often means larger surprise costs. If you do not have one yet, start small. Even a modest amount set aside regularly can help keep a rough week from becoming a money crisis.

A Calm Way to Start

That is a full list, and you do not have to tackle it all at once. Pick one item this week. Maybe it is checking a beneficiary, or asking work about adding your baby to your benefits. Small steps, taken one at a time, can help build a stronger financial foundation for your growing family.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

  • Registered Education Savings Plan (RESP) – Government of Canada

  • Canada Education Savings Grant (CESG) – Government of Canada

  • EI Maternity and Parental Benefits – Government of Canada

  • Making a Will and Power of Attorney – Government of Canada

https://aquafinancialconsulting.com/wp-content/uploads/2026/06/Financial-Checklist-for-New-Parents-FI.png 700 1200 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2026-06-30 16:13:312026-06-30 16:14:09Financial Checklist for New Parents in Canada

What Is Participating Whole Life Insurance?

June 1, 2026/in 2026, Blog, Insurance/by Aquafinancial Consulting

What Is Participating Whole Life Insurance?

Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.

Here is what it means, how it works, and whether it might be a fit for you.

Permanent Coverage That Does Not Expire

Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.

That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.

With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.

How Dividends Work

The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.

These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.

When you receive a dividend, you have a few options for how to use it:

  • Take it as cash. The dividend is paid to you directly.

  • Apply it to your premium. It reduces how much you pay out of pocket.

  • Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.

  • Leave it on deposit. The dividend sits with the insurer and earns interest.

Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.

The Cash Value

One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.

The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:

  • Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.

  • Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.

The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.

Who Is This Type of Policy For?

Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.

Some of the most common situations where it makes sense:

Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.

Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.

Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.

High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.

How It Fits Alongside Term Insurance

Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.

Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.


Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.

What to Take Away

Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.

If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.
This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.

Sources:

Participating Life Insurance – CLHIA

https://aquafinancialconsulting.com/wp-content/uploads/2026/06/WhatisWholLifeFI.png 700 1200 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2026-06-01 13:37:502026-06-01 13:38:17What Is Participating Whole Life Insurance?

Corporate Life Insurance Planning

September 3, 2025/in Blog, Business owners, Insurance, Life insurance, Professional Corporations/by Aquafinancial Consulting

Corporate Life Insurance Planning: Protect, Reward, and Plan for the Future

Running a business in often means wearing multiple hats—owner, leader, and long-term planner. But have you ever thought about what happens if you or a key person in your company passes away unexpectedly? Or how you might use your corporation to support retirement, reward top talent, or prepare for taxes when transitioning ownership?

Corporate life insurance is one of the most flexible and underused tools available to business owners. It helps protect your company, reduce taxes, and build lasting value—both during your working years and when it’s time to pass the business on.

Let’s look at how business owners are using corporate-owned life insurance to protect their companies and their families while preparing for the future.

brandableContent

Succession Planning: Make Transitions Smooth and Tax-Smart

For many business owners, their company is one of their largest assets. But passing it on—whether to family or a partner—comes with major financial challenges. Life insurance can help.

Funding a Buy-Sell Agreement

If you have a business partner, a buy-sell agreement ensures that if one of you passes away, the other can buy the shares from the deceased’s estate. The problem? That buyout requires cash—often hundreds of thousands, if not millions. Life insurance is a cost-effective way to fund that agreement, so ownership stays in the right hands without putting a strain on the business or the family.

Covering Final Taxes and Capital Gains

When a business owner dies, the Canada Revenue Agency treats it as if they sold their shares—even if they didn’t. This “deemed disposition” creates a tax bill that can surprise even the most prepared families. Life insurance provides a tax-free lump sum that the corporation can use to cover this cost, helping preserve the value of the business and avoid selling off assets under pressure.

Estate Equalization

If you plan to leave the business to one child but want to treat your other children fairly, life insurance can help. The business goes to the child who’s involved, while other beneficiaries receive the life insurance proceeds. It’s a clean, tax-efficient way to avoid family conflict and keep the business whole.

Executive Compensation: Attract and Retain Top Talent

In a competitive hiring environment, offering the right benefits can make all the difference. Life insurance isn’t just about protection—it can be a powerful way to reward and retain your most valuable people.

Executive Compensation Strategies

Life insurance can be part of a compensation package that rewards top performers, especially those who are key to the company’s success. Whether structured as a bonus plan or part of a long-term incentive, this can be a powerful way to align goals and build loyalty.

Retirement Funding

Permanent life insurance policies (like whole life or universal life) build cash value over time. That value grows tax-deferred and can be accessed through policy loans or collateralized lending. Business owners and executives often use this as an additional retirement income stream, especially if they’ve already maxed out RRSP or TFSA contributions.

Tax-Sheltered Wealth Accumulation

The cash value inside a permanent life insurance policy grows on a tax-deferred basis. When a corporation owns the policy, this growth can be especially strategic. It allows the business to use surplus cash to build value in a tax-efficient way, diversify beyond traditional investments, and potentially access funds later with fewer tax consequences. This approach is particularly useful for businesses with retained earnings that would otherwise be subject to higher corporate tax rates.

Business Continuity: Protect What You’ve Built

An unexpected death can do more than cause emotional pain—it can disrupt operations, shake client confidence, and even put the business at risk. Insurance helps ensure your company can keep going.

Key Person Protection

If you or someone else is essential to the day-to-day success of your business, losing that person could be a major financial blow. A life insurance policy on that individual can help the business recover, cover short-term losses, and fund the search for a replacement.

Business Loan Protection

Many lenders require insurance on owners or key executives as a condition of financing. If that person passes away, life insurance ensures the loan is paid off, protecting both the lender and the company’s assets. It can also unlock better lending terms and help avoid personal guarantees.

Charitable Giving Through the Corporation

For business owners looking to give back, corporate life insurance can also be used to support charitable causes. The business can own a policy and name a charity as the beneficiary—creating a lasting impact while offering potential tax benefits.

Bringing It All Together

Corporate life insurance isn’t just about “what if”—it’s about building a stronger, more resilient business and unlocking smart ways to manage wealth inside your company. Whether you’re focused on succession, rewarding your team, or protecting operations, insurance can help you take action today that pays off for years to come.

If you haven’t reviewed your corporate insurance strategy recently, now’s a great time to take a fresh look.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

https://aquafinancialconsulting.com/wp-content/uploads/2025/09/Corporate-Life-Insurance-Planning-FI-1.png 700 1200 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2025-09-03 23:33:592025-09-03 23:43:47Corporate Life Insurance Planning

What is disability insurance?

August 6, 2024/in Blog, Business owners, Disability, disability insurance, Family, farmers, financial advice, Health benefits, incorporated professionals, Individuals, Insurance, Professionals/by Aquafinancial Consulting

If you cannot work because you are seriously injured or ill, disability insurance will provide you with a monthly, tax-free income to help replace your lost wages.  An injury does not have to be as blatant as a broken leg or arm – suffering from chronic pain or dealing with mental health issues can also qualify you for a disability insurance payout.  

Why do I need disability insurance?

Unfortunately, people become disabled – whether temporarily or permanently – quite often. In 2017, over 20 percent of Canadians had one or more disabilities. 

If you’re disabled, you may lose one of your most valuable assets – your ability to work and bring in a paycheck. Disability insurance can help replace that paycheck for as long as you need it to. Being able to rely on a disability insurance payout means you won’t have to dip into your savings if anything happens to you.

Disability insurance is especially important if you are self-employed, particularly if you are the family’s sole income earner.

What if I already have disability insurance through work?

If you have disability insurance through work, that’s great – but it may not replace 100 percent of your paycheck, especially if you’re off work for a long time. If you purchase private disability insurance, you can:

  • Choose how much coverage you want.
  • Adjust your coverage as needed.
  • Not have to worry if you leave your employer – you won’t lose your disability insurance coverage.

Having private disability insurance will give you peace of mind that you either have additional coverage if you are employed and at least some disability coverage if you lose your job.

How does disability insurance work?

We’d be happy to answer any questions you have about disability insurance. There are five main steps to disability insurance:

  1. Determine the amount of coverage you want. The higher your salary, the more coverage you should get.
  2. Pay your monthly premiums. Factors like your health, your age, and the amount of coverage you have will all impact the cost of your premiums.
  3. File a claim if you become disabled – we can help you with this.
  4. Receive your monthly payments once your waiting period has passed – a longer waiting period can lower your premiums, but it does mean you’ll go longer without any income.
  5. When you are healthy enough to return to work, or your coverage period runs out, you will stop receiving disability insurance payments.

We’re Here To Help

If you’d like to know more about disability insurance – from how much it would cost you to what you can file a claim for – we’re here to help! Give us a call today.

https://aquafinancialconsulting.com/wp-content/uploads/2024/08/What-is-disability-insurance.jpg 300 500 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2024-08-06 06:00:152024-08-06 17:46:59What is disability insurance?

Network of Professionals

June 3, 2024/in Accountants, Blog, Business owners, Center of Influences, Estate planning, Family, farmers, financial advice, financial planning, incorporated professionals, Individuals, Insurance, Investment, Life insurance/by Aquafinancial Consulting

Our Network of Professionals

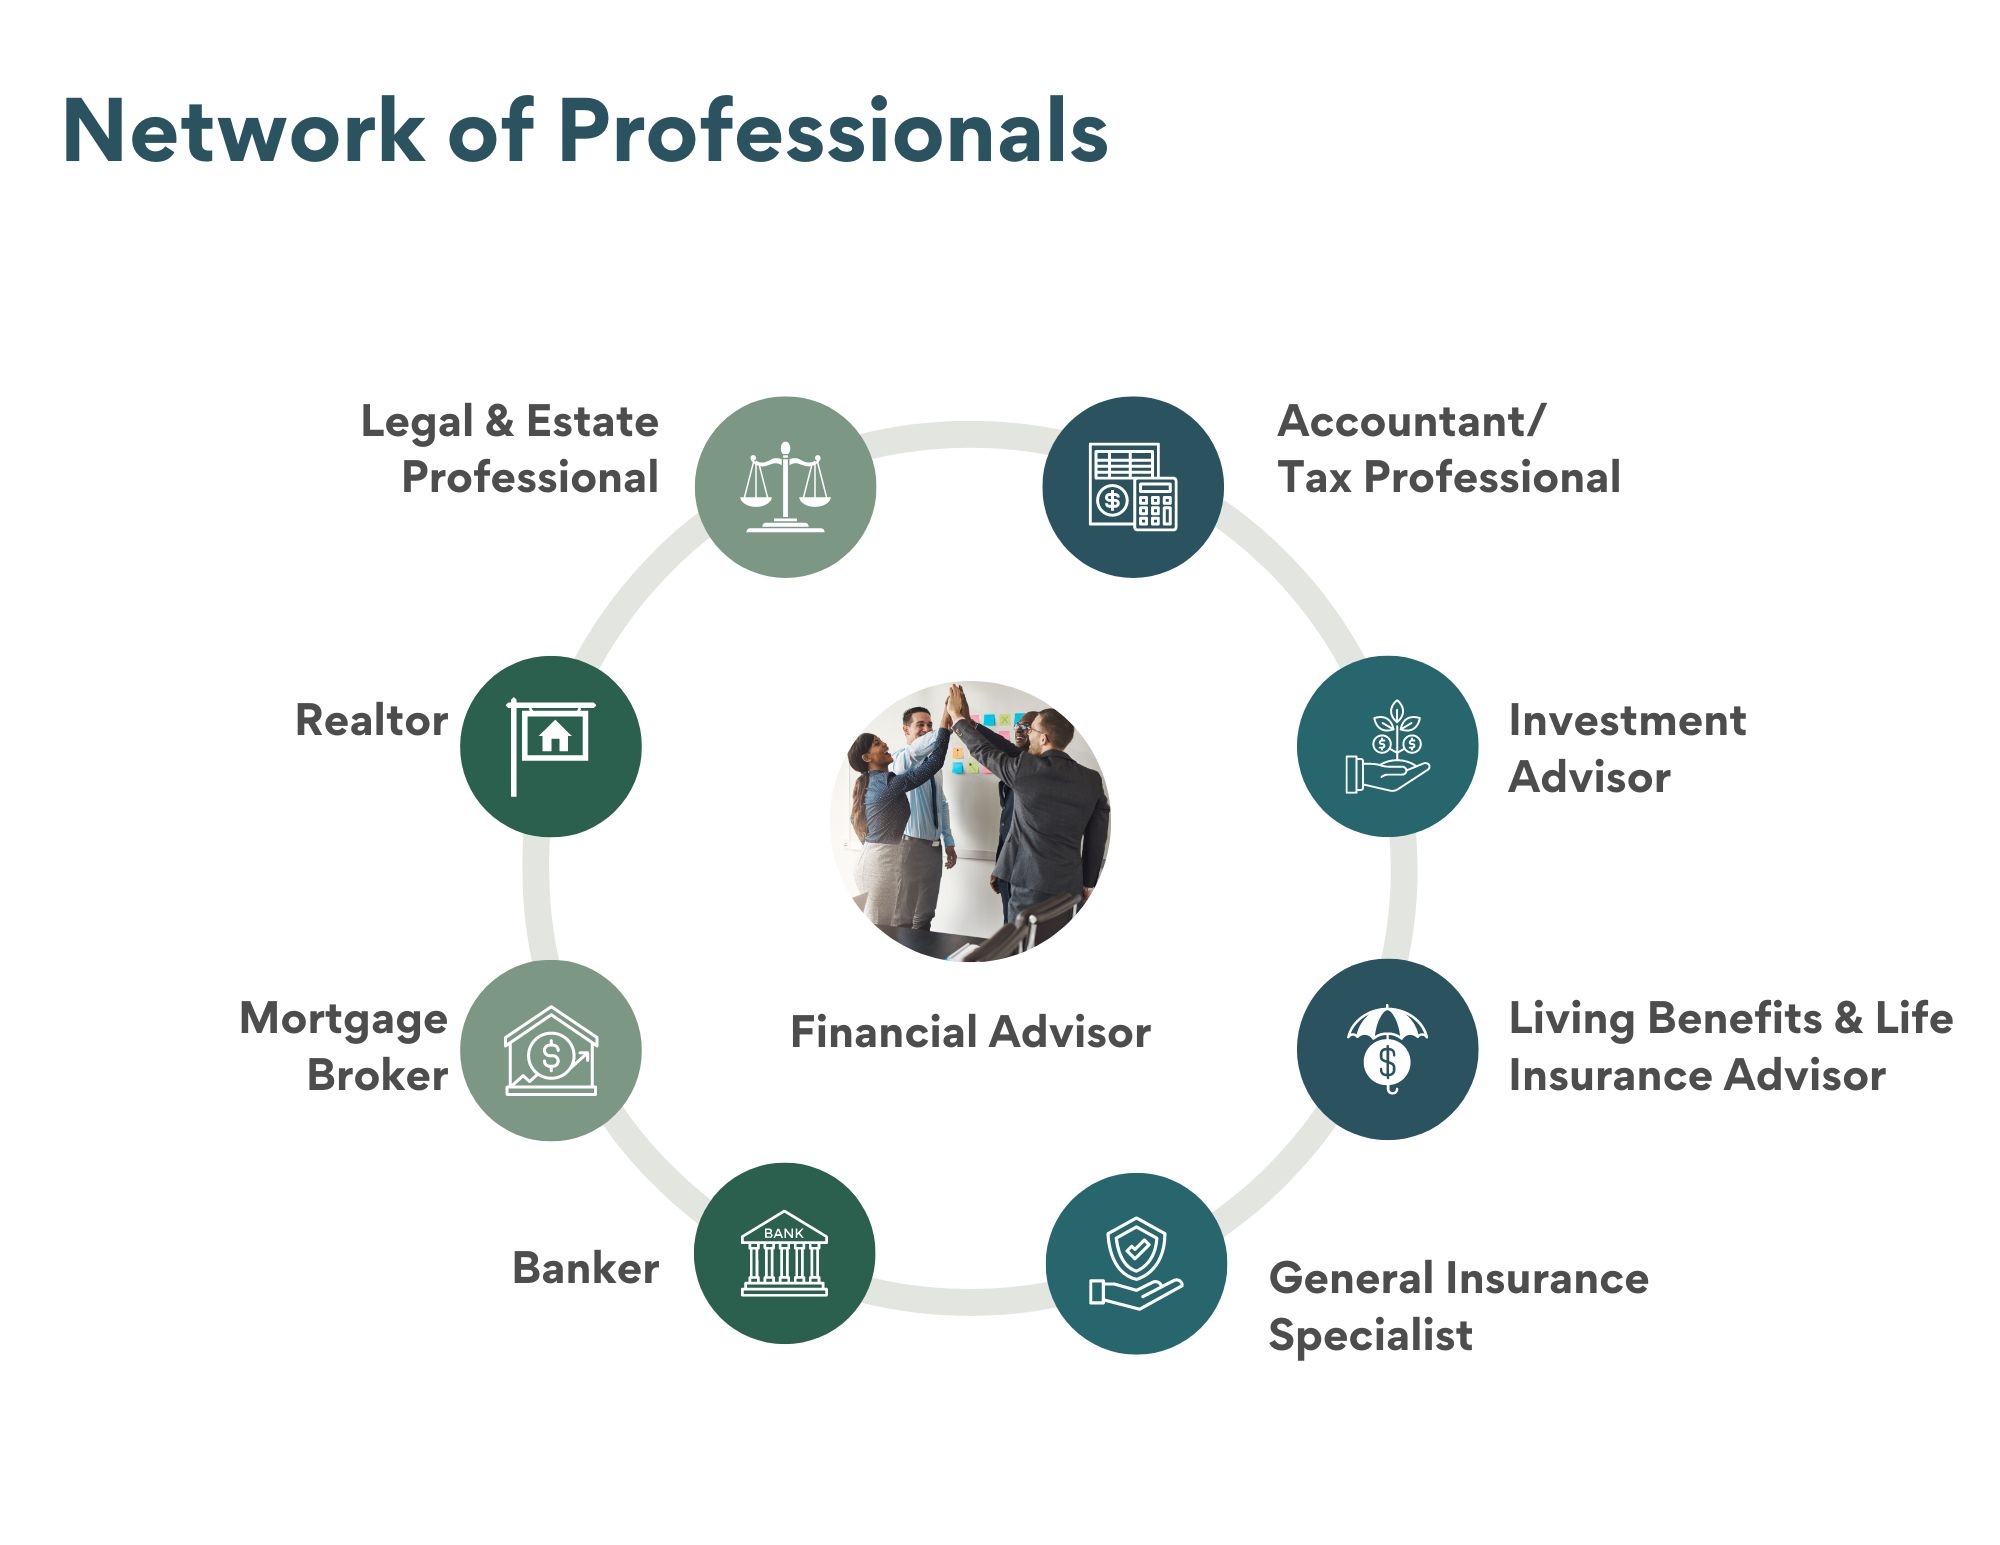
As a financial advisor, my primary goal is to help you achieve financial clarity. I do this by accessing a network of dedicated professionals, each bringing their unique expertise to the table. Together, we provide personalized advice and services that help you make informed decisions and secure your future.

Financial Advisor

Think of me as your financial coordinator. I help you figure out your goals, create plans to achieve them, and keep everything on track. Whether it’s planning for retirement, managing investments, or saving for a major purchase, I have access to a network of professionals who ensure every aspect of your financial life works together smoothly.

Accountant/Tax Professional

Having an accountant or tax professional in your financial network is essential for keeping your financial records in order. They handle tasks like bookkeeping, preparing financial statements, and assisting with tax planning. Their role is particularly important during tax season. They help you file your taxes accurately and on time, taking the stress out of the process. By optimizing your tax strategies and ensuring everything is reported correctly, they help you save money. Their skills are invaluable for both your immediate needs and long-term financial planning.

Investment Advisor

Investment advisors focus on building and managing investment portfolios tailored to your short-term, medium-term, and long-term goals. They thoroughly research the market, evaluate investment opportunities, and offer valuable insights to help you create a well-rounded portfolio. Whether you’re saving up for a major purchase, planning for retirement, or aiming for other financial milestones, they assist in choosing the right investment vehicles, such as RRSPs, TFSAs, RRIFs, and non-registered accounts, to support your financial stability and future needs.

Life Insurance and Living Benefits Advisor

Life insurance and living benefits advisors are here to help you protect your greatest asset: yourself. Their job is to make sure you and your family are financially secure if unexpected events occur. These advisors walk you through different insurance options, including disability insurance, critical illness insurance, and life insurance, to find the coverage that fits your needs best. By understanding your unique situation and recommending the right policies, they provide you with peace of mind, knowing that you have a safety net in place for life’s uncertainties.

General Insurance Specialist

General insurance specialists cover a wide range of insurance needs, including auto, property, travel, and liability insurance. They assess your risks and recommend policies that provide the protection you need. Their advice helps you understand your options, compare quotes, and select the best policies to safeguard your assets, ensuring you are well-protected in various aspects of your life.

Banker

Bankers are there to help you navigate a wide range of financial services, especially when it comes to getting loans and credit products. They offer advice on securing personal loans, understanding credit options, and managing debt effectively. Whether you’re looking to finance a major purchase, consolidate debt, or build your credit, bankers provide the support and guidance you need to make informed financial decisions.

Mortgage Broker

Mortgage brokers assist you in securing financing for property purchases by accessing multiple lenders on your behalf. They assess your financial situation, compare mortgage products from various sources, and recommend the best options for you. With their ability to shop around and understand different interest rates, loan terms, and application processes, they ensure you get the best possible mortgage deal, making homeownership more accessible and affordable.

Realtor

Realtors are your go-to professionals for buying or selling property. They provide market insights, negotiate deals, and manage the legal aspects of real estate transactions. With their knowledge of local market trends and property values, realtors help you make informed decisions whether you’re purchasing a home, investing in real estate, or selling property.

Legal & Estate Professional

Legal and estate professionals play a vital role in your financial planning by handling the legal side of things, such as estate planning, wills, trusts, and probate. They make sure your assets are distributed according to your wishes and that all the necessary legal documents are properly set up. Their guidance helps you reduce estate taxes and smoothly navigate the legal processes, ensuring your wealth is transferred to future generations just as you intended.

Having a network of financial professionals is essential for achieving financial well-being. Each member brings their own expertise to address different aspects of your finances, from investments and insurance to legal and real estate matters. As your financial advisor, I act as the coordinator, ensuring that all these professionals work together seamlessly. By leveraging their combined knowledge and skills, you can gain financial clarity and know that every aspect of your financial life is taken care of.

Ready to take control of your financial future? Contact us today.

https://aquafinancialconsulting.com/wp-content/uploads/2024/06/Network-of-Professionals-FI.png 700 1200 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2024-06-03 12:01:592024-06-03 12:47:42Network of Professionals

The Health Spending Account for Business Owners and Incorporated Professionals

May 1, 2024/in Blog, financial advice, financial planning, Insurance/by Aquafinancial Consulting

Are you tired of using your hard-earned after-tax dollars to cover medical expenses? As a business owner, the burden of managing healthcare costs can be overwhelming. However, there’s a little-known solution that can alleviate this financial strain – the Health Spending Account.

Designed specifically for entrepreneurs like you, the Health Spending Account offers a tax-efficient way to manage medical expenses. Say goodbye to paying out of pocket with after-tax dollars for your healthcare needs, and let’s explore the advantages of this specialized account tailored to meet the unique needs of business owners and incorporated professionals.

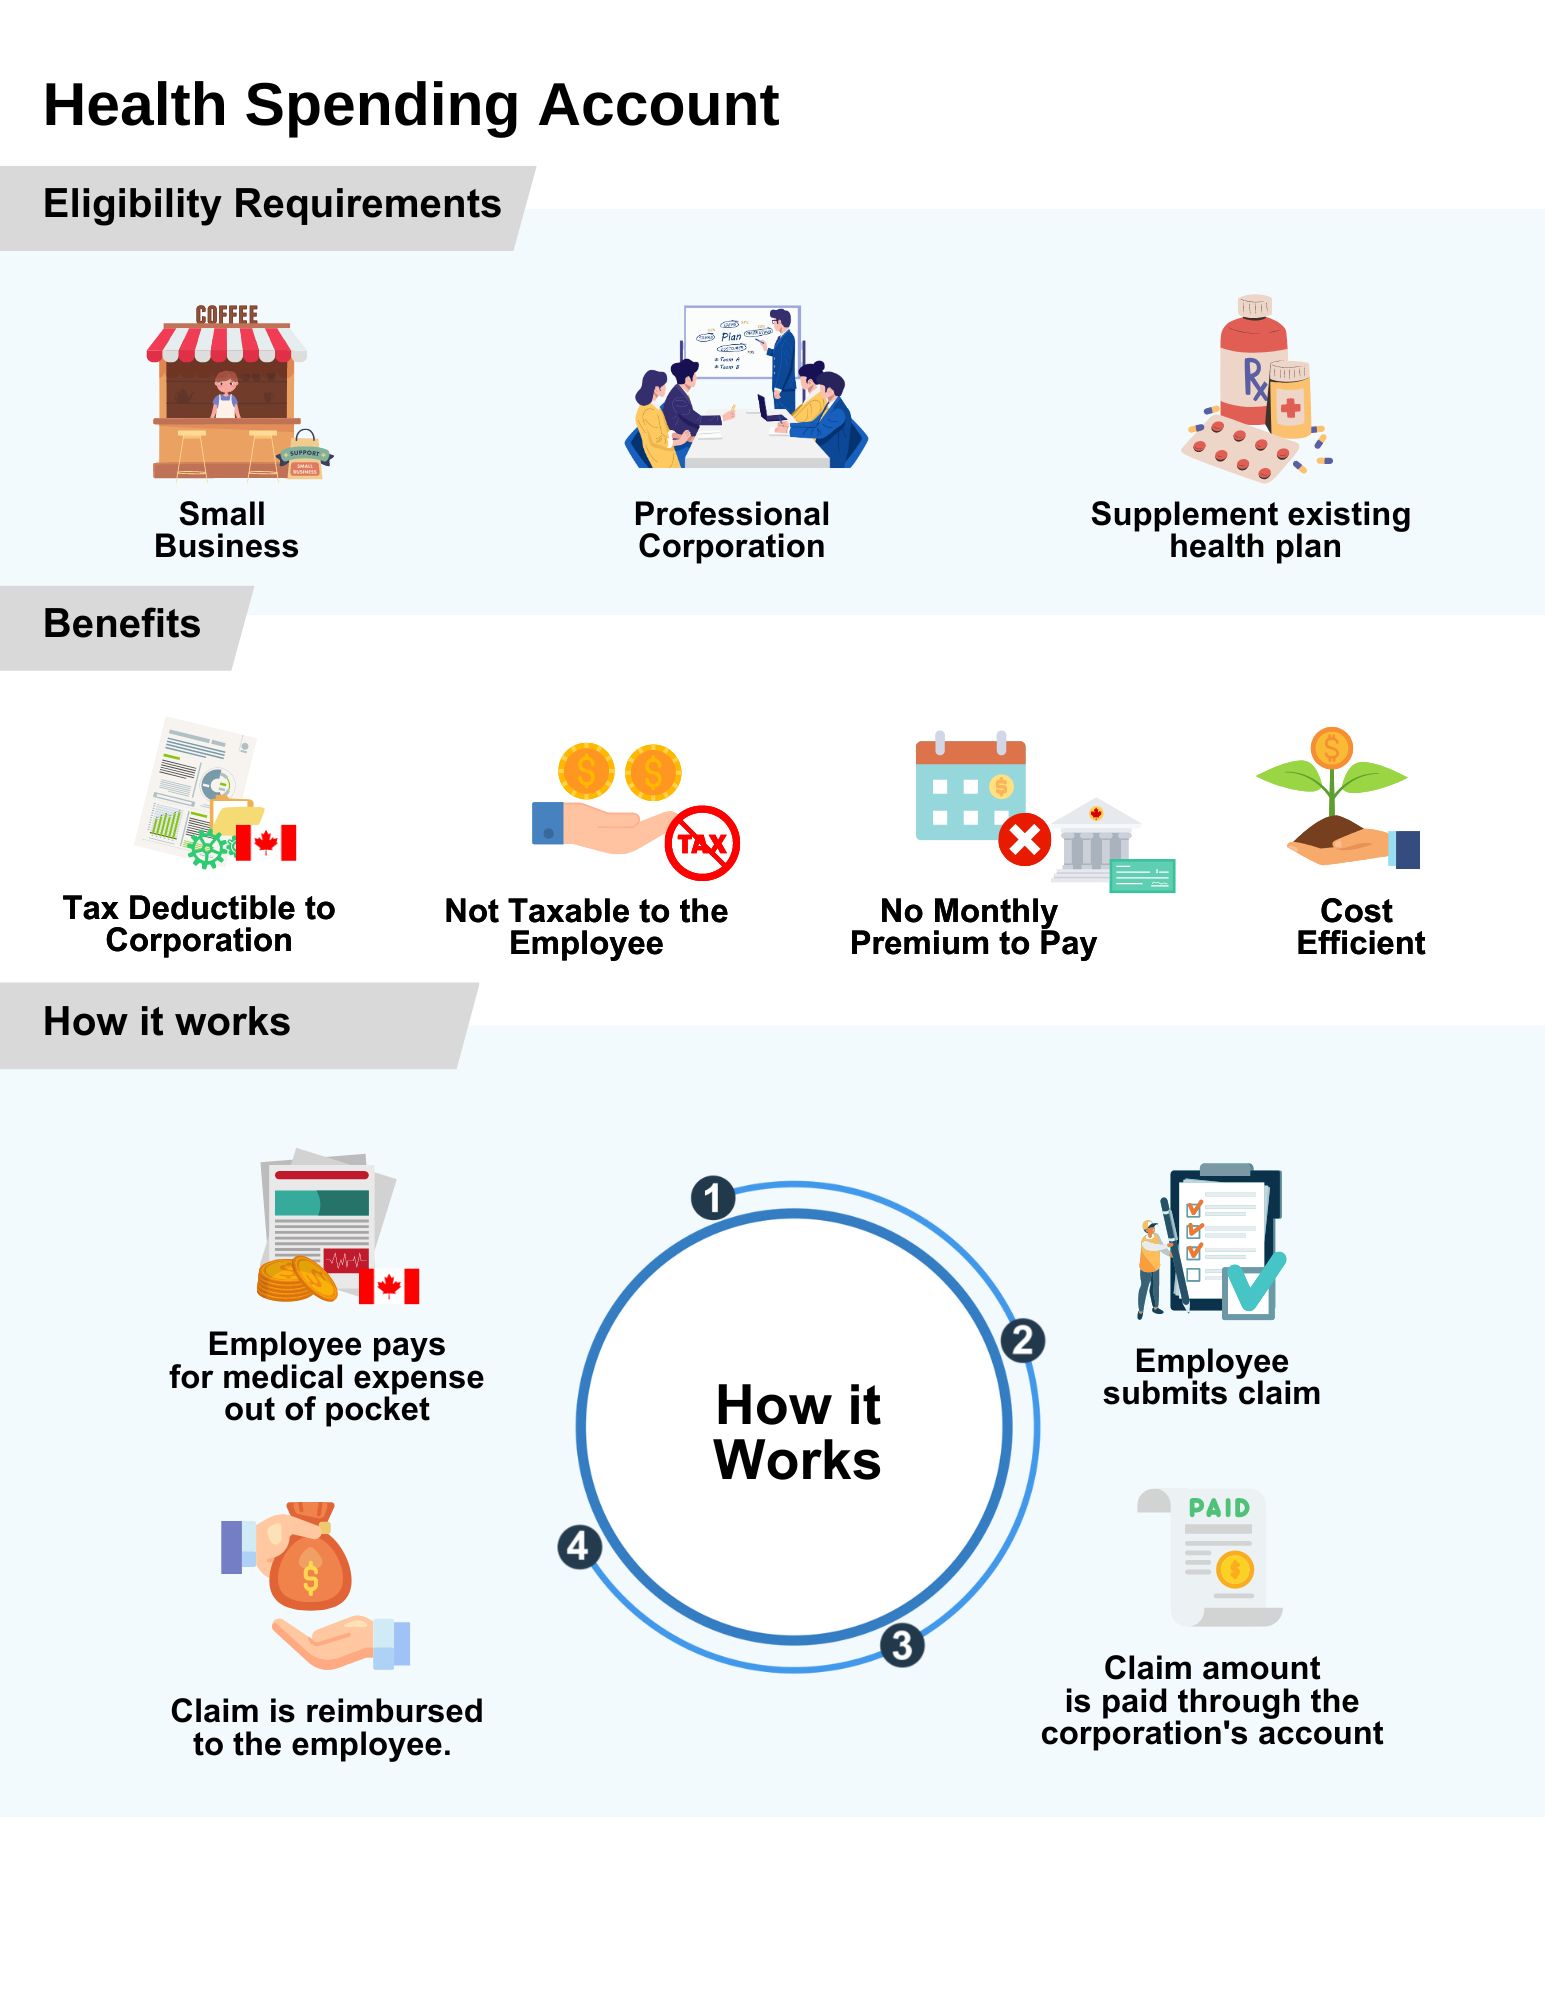
Who’s eligible?

The Health Spending Account is available to a wide range of businesses, making it an inclusive and flexible solution. Small businesses, professional corporations, and corporations that wish to supplement an existing health plan are all eligible to participate in this program. Whether you run a small family-owned enterprise, a professional practice, or a larger corporate entity, the Health Spending Account can cater to your specific needs and provide valuable healthcare benefits for you and your employees.

What are the benefits?

Tax Deductibility for Corporations

As a business owner or incorporated professional, you know the significance of minimizing tax burdens. The Health Spending Account allows your corporation to make contributions that are 100 percent tax-deductible. By taking advantage of this tax benefit, you can reduce your corporation’s taxable income, resulting in lower overall taxes. This leaves you with more funds to reinvest in your business, expand operations, or reward your hardworking employees.

Tax-Free Benefits for You and Your Employees

The Health Spending Account offers tax-free reimbursements for both you, as the business owner or incorporated professional, and your employees. Any medical expense covered through the account is received as tax-free income. This means you get to retain more of your earnings while providing valuable healthcare benefits to your workforce without increasing their taxable income. It’s a win-win situation that fosters employee satisfaction and loyalty.

No monthly premium to pay and cost-efficient

A Health Spending Account (HSA) offers a highly cost-efficient approach to managing medical expenses, providing individuals and businesses with significant financial advantages. One of the key benefits of an HSA is that there is no monthly premium to pay, unlike traditional health insurance plans. This means that participants can access valuable healthcare benefits without the burden of regular premium payments. With no ongoing costs, the HSA allows individuals and businesses to allocate their funds more strategically, ensuring that their healthcare budget is utilized efficiently. This cost-effective feature makes the Health Spending Account an attractive option for those seeking to optimize their healthcare spending while enjoying comprehensive medical coverage.

How it works

The Health Spending Account simplifies the process of managing healthcare expenses:

1. Employees pay for medical services out of pocket.

2. The employee submits the claim for reimbursement.

3. The claim amount is then reimbursed tax-free through the corporation’s account.

4. The claim is reimbursed to the employee.

This streamlined process eliminates the complexities associated with traditional health insurance plans, saving you time and effort.

To learn more about how a health spending account can benefit you, please reach out today to book a meeting, and we would be happy to help.

https://aquafinancialconsulting.com/wp-content/uploads/2024/05/FIND-MORE-MONEY.jpg 300 600 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2024-05-01 06:00:132024-05-01 14:47:23The Health Spending Account for Business Owners and Incorporated Professionals

Insurance Planning for Incorporated Professionals

December 1, 2022/in Blog, Buy Sell, critical illness insurance, disability insurance, group benefits, Health benefits, incorporated professionals, Insurance, Life insurance, travel insurance/by Aquafinancial Consulting

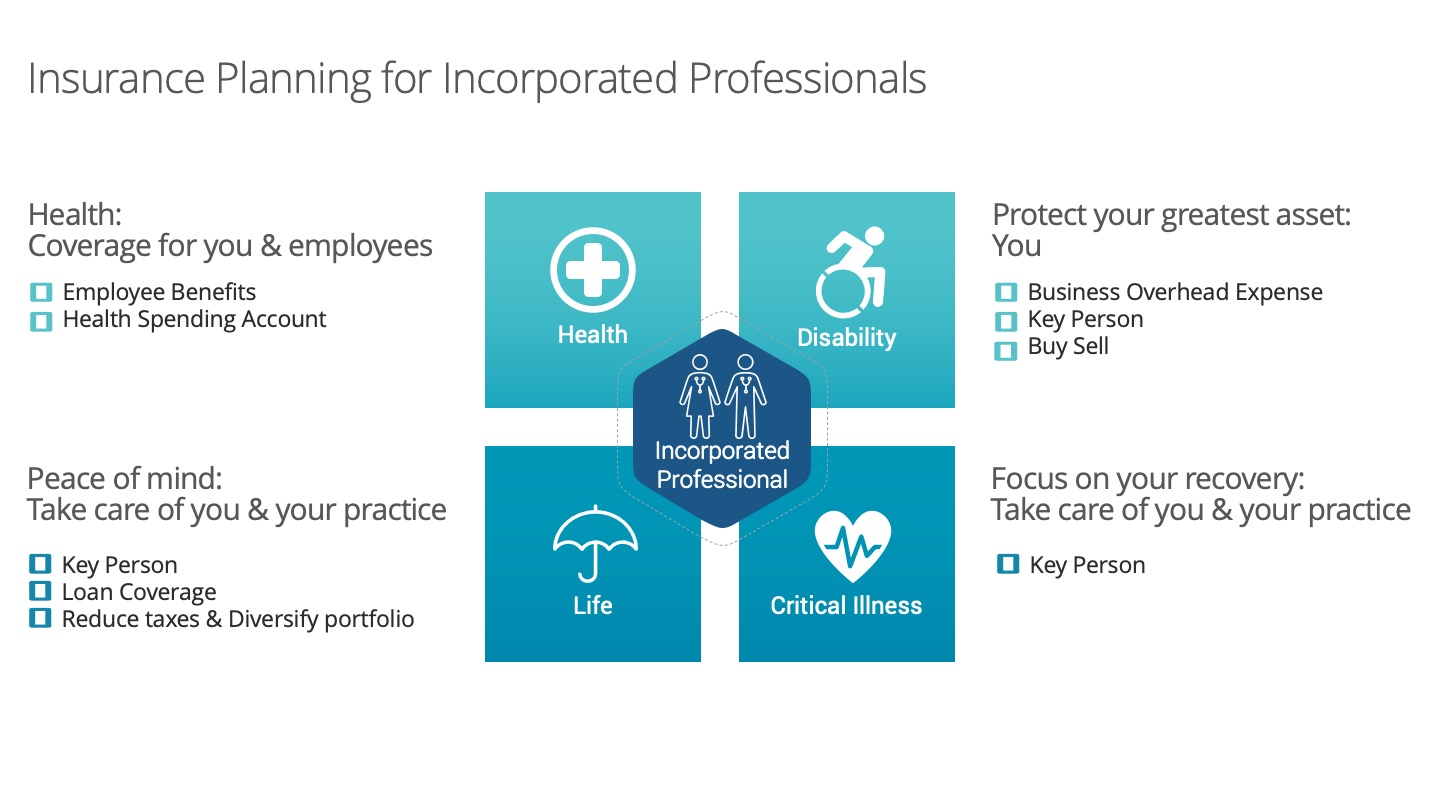
For incorporated professionals, making sure your practice is financially protected can be overwhelming. Incorporated professionals face a unique set of challenges when it comes to managing risk. Insurance can play an important role when it comes to reducing the financial impact on your practice in the case of uncontrollable events such as disability, or critical illness. This infographic and article address the importance of corporate insurance.

The 4 areas of insurance a incorporated professional should take care of are: 

  • Health 

  • Disability 

  • Critical Illness 

  • Life

Health: We are fortunate in Canada, where the healthcare system pays for basic healthcare services for Canadian citizens and permanent residents. However, not everything healthcare related is covered, in reality, 30% of our health costs* are paid for out of pocket or through private insurance such as prescription medication, dental, prescription glasses, physiotherapy, etc.

For incorporated professionals, offering employee health benefits make smart business sense because health benefits can form part of a compensation package and can help retain key employees and attract new talent.

For incorporated professionals that are looking to provide alternative health plans in a cost effective manner, you may want to consider a health spending account.

Disability: Most people spend money on protecting their home and car, but many overlook protecting their greatest asset: their ability to earn income. Unfortunately one in three people on average will be disabled for 90 days or more at least once before the age of 65.

Consider the financial impact this would have on your practice if you or a key employee were to suffer from an injury or illness. Disability insurance can provide a monthly income to help keep your practice running.

Business overhead expense insurance can provide monthly reimbursement of expenses during total disability such as rent for commercial space, utilities, employee salaries and benefits, equipment leasing costs, accounting fees, insurance premiums for property and liability, etc.

Key person disability insurance can be used to provide monthly funds for you or key employee while they’re disabled and protect the business from lost revenue while your business finds and trains an appropriate replacement.

Critical Illness: For a lot of us, the idea of experiencing a critical illness such as a heart attack, stroke or cancer can seem unlikely, but almost 3 in 4 (73%) working Canadians know someone who experience a serious illness. Sadly, this can have serious consequences on you, your family and business, with Critical Illness insurance, it provides a lump sum payment so you can focus on your recovery.

Key person critical illness insurance can be used to provide funds to the practice so it can supplement income during time away, cover debt repayment, salary for key employees or fixed overhead expenses.

Buy sell critical illness insurance can provide you with a lump sum payment if your business partner or shareholder were to suffer from a critical illness. These funds can be used to purchase the shares of the partner, fund a buy sell agreement and reassure creditors and suppliers.

Life: For an incorporated professional, not only do your employees depend on you for financial support but your loved ones do too. Life insurance is important because it can protect your practice and also be another form of investment for excess funds.

Key person life insurance can be used to provide a lump sum payment to the practice on death of the insured so it can keep the business going until you an appropriate replacement is found. It can also be used to retain loyal employees by supplying a retirement fund inside the insurance policy.

Loan coverage life insurance can help cover off any outstanding business loans and debts.

Reduce taxes & diversify your portfolio, often life insurance is viewed only as protection, however with permanent life insurance, there is an option to deposit excess funds not needed for operations to provide for tax-free growth (within government limits) to diversify your portfolio and reduce taxes on passive investments.  

Talk to us to make sure you and your practice are protected.

Contact Us
https://aquafinancialconsulting.com/wp-content/uploads/2022/12/insurancePlanningFI.jpeg 810 1440 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2022-12-01 06:00:002022-12-01 08:20:59Insurance Planning for Incorporated Professionals

Why Insurance Is So Important If You’re A Single Parent

July 6, 2022/in Blog, Family, Insurance, Life insurance/by Aquafinancial Consulting

Why Insurance Is So Important If You’re A Single Parent

Your kids mean everything to you – and you want to make sure they’re protected no matter what. As a single parent, you must have the right health and life insurance options in place to make that happen. We recommend you consider all of the following types of insurance:

  • Disability insurance

  • Critical illness insurance

  • Accident insurance

  • Life insurance

Disability insurance

Disability insurance can provide you with an income if you become disabled and cannot work – whether it’s for a short period of time or a long one.

Most workplaces offer disability coverage, but it’s tied to that particular job, so you’ll lose coverage if you leave that job. As well, the coverage from your employer’s plan may not be sufficient to cover your needs if you become disabled.

It’s particularly important for you to look into disability insurance if you work as a contractor or have a job with no benefits.

Critical illness insurance

Critical illness insurance can help you pay for the costs associated with various serious medical issues (such as a heart attack, cancer, or a stroke) that aren’t covered by any other health plans or disability insurance. As a single parent, you may find the payout from a critical illness insurance policy especially helpful for paying for extra childcare or lost income if you cannot work.

Accident insurance

Life is getting busier than ever – and there are more and more of us on the roads. Unfortunately, more people on the roads mean more accidents. If you buy accident insurance for yourself or your children, the payout from the policy can bring in some extra income at a critical time of need if any of you are in an accident. You can use an accident insurance payout to help pay for anything from lost income to private home care.

Life insurance

Life insurance is critical as a single parent as your children are dependent on your income. Generally, we suggest that you get a policy that is worth at least 10 times your annual income, but you may need more if you have a lot of debt or you need the money to last a long time.

Your children should be the beneficiaries of your policy and you can name a trustee (such as a grandparent or other relative) to look after the money on your children’s behalf until they reach a specified age.

We can help!

If you have questions about what kind of insurance is best for you, we’re happy to answer them! We’ll walk you through all your options and put together an insurance package that’s just right for you. Call us today!

https://aquafinancialconsulting.com/wp-content/uploads/2022/07/Why-Insurance-is-so-important.png 281 500 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2022-07-06 06:00:002022-07-06 16:34:40Why Insurance Is So Important If You’re A Single Parent

2022 Federal Budget Highlights

April 8, 2022/in Blog, Insurance, Investment/by Aquafinancial Consulting

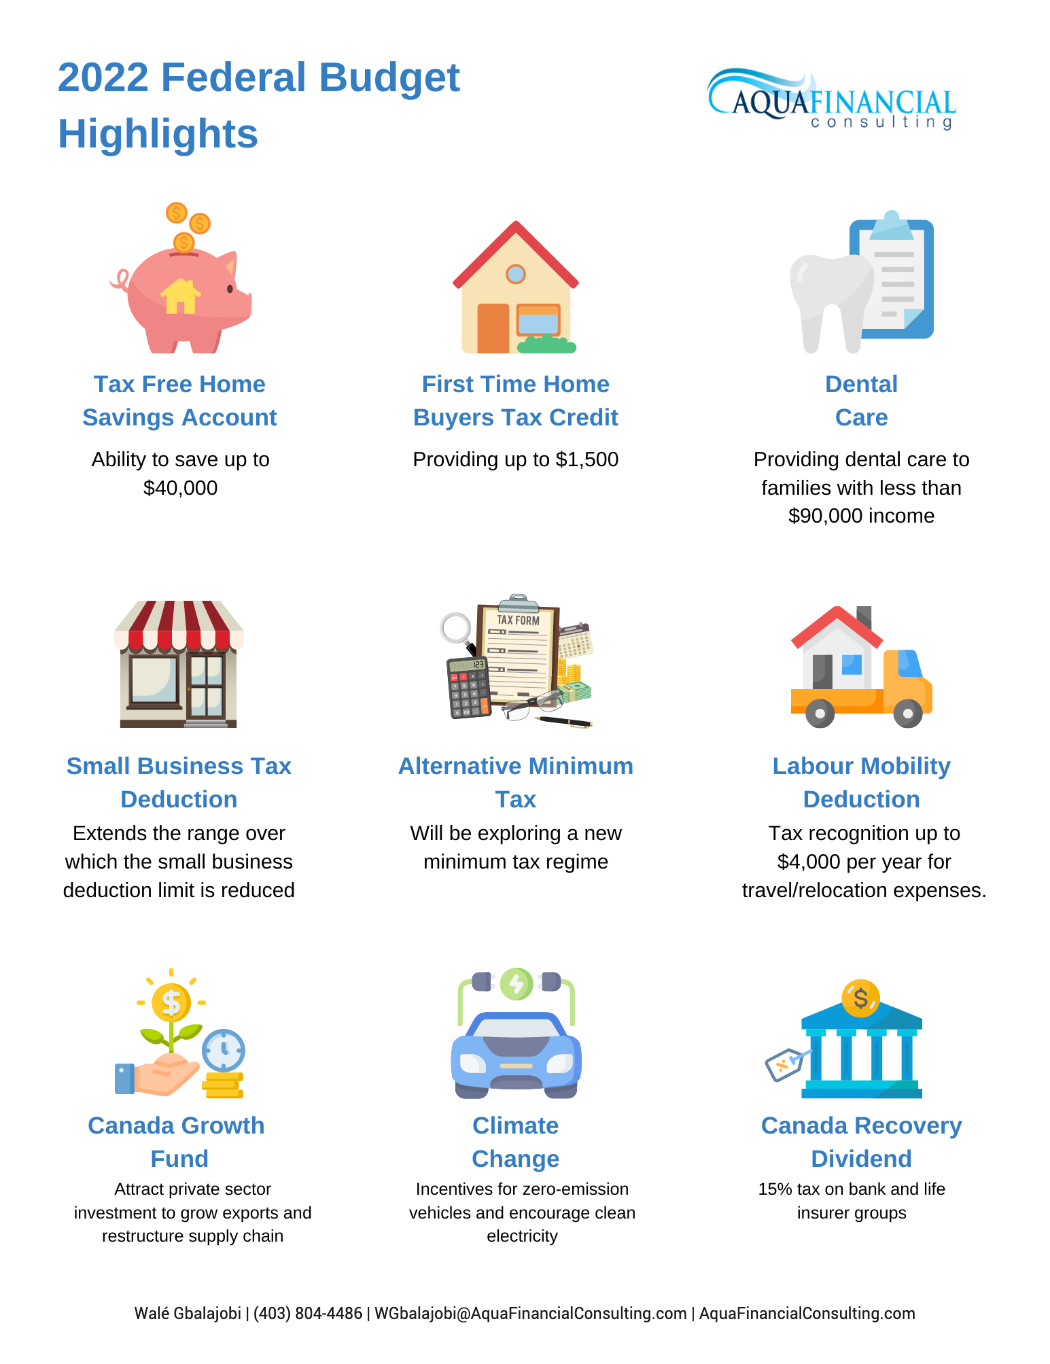
Federal Budget 2022 – Highlights

On April 7, 2022, the Federal Government released their 2022 budget. We have broken down the highlights of the financial measures in this budget into the following different sections:

  • Housing

  • Alternative minimum tax

  • Dental care

  • Small businesses

  • Tradespeople

  • Canada Growth Fund

  • Climate

  • Bank and insurer taxes

Housing

There were several tax measures related to housing introduced in the budget.

Budget 2022 introduced a new kind of savings account – a Tax-Free First Home Savings Account (FHSA).

These are the key things you need to know about the new FHSAs:

  • You must be at least 18 years of age and a resident of Canada to open an account. You must also not currently own a home or have owned one in the previous four calendar years.

  • You can only open and use an FHSA once, and you must close it within a year after your first withdrawal.

  • Contributions are tax-deductible, and income earned in an FHSA will not be either while it is in the account or when you withdraw it.

  • There is a lifetime contribution limit of $40,00, with an annual contribution limit of $8,000. You can’t carry contribution room forward.

  • If you don’t use the funds in your FHSA within 15 years of opening it, you can transfer them to an RRSP or RRIF tax-free. Transfers to an RRSP do not impact your RRSP contribution room.

Two existing tax credits were increased, and a new one was introduced:

  • The First-Time Home Buyers’ Tax Credit amount was increased from $5000 to $10,000, giving up to $1,500 in direct support to home buyers. This tax credit applies to all homes purchased on or after January 1, 2022.

  • The annual expense limit for the Home Accessibility Tax Credit has been increased to $20,000 for 2022 and subsequent tax years.

  • A new tax credit, the Multigenerational Home Renovation Tax Credit, was introduced, which will start in 2023. This tax credit is a 15% refundable credit for eligible expenses up to $50,000 (maximum tax credit is $7,500) for constructing a secondary suite for a senior or an adult with a disability to live with a qualifying relative.

Budget 2022 proposes new rules, effective January 1, 2023, that anyone who sells a residential property they have held for less than 12 months would be subject to full taxation on their profits as business income. However, there will be some exemptions to these rules due to life events such as a death, disability, the birth of a child, a new job, or a divorce.

Budget 2022 also announces restrictions that would help ensure that Canadians, instead of foreign investors, own housing. A two-year ban will be introduced on non-residents buying residential property, with some exceptions, such as individuals who have work permits and are living in Canada.

Alternative Minimum Tax

In Canada, the top federal tax rate is 33% and starts at an income of $221,708. However, many high-income filers end up paying less tax than this due to tax deductions and tax credits.

The goal of the Alternative Minimum Tax (AMT), which has been around since 1986, is to ensure high-income Canadians are paying their fair share of taxes. However, it has not been substantially updated since it was introduced. In Budget 2022, the government indicated they would be investigating changes to the AMT, which will likely be disclosed in the fall 2022 economic update.

Dental Care

For many Canadians without private coverage, going to the dentist is too expensive. Budget 2022 commits $5.3 billion to provide dental care for Canadians with family incomes of less than $90,000 annually. Coverage will start for children under 12 this year and expand to children under 18, seniors and those living with a disability in 2023, with the program will be fully implemented by 2025.

Small Businesses

Small businesses currently have a 9% tax rate on the first $500,000 of taxable income (compared to the corporate tax rate of 15%). However, after a small business’ capital employed in Canada reaches $15 million, it is no longer eligible for the 9% tax rate.

Budget 2022 proposes gradually phasing out the small business tax rate so that businesses are not discouraged from expanding. The new cut-off for the lower tax rate will be $50 million.

Budget 2022 also includes a proposal to create an Employee Ownership Trust. This would be a new, dedicated trust under the Income Tax Act to support employee ownership.

Tradespeople

Budget 2022 introduces the Labour Mobility Deduction. This would allow eligible tradespersons and apprentices to deduct up to $4,000 a year in eligible travel and temporary relocation expenses.

Budget 2022 also commits to providing $84.2 million over four years to double funding for the Union Training and Innovation Program, which would help 3,500 apprentices from underrepresented groups each year.

Canada Growth Fund

Budget 2022 introduces a new Canada Growth Fund, with the goals of both diversifying our economy and helping achieve our climate goals.

The Canada Growth Fund aims to attract considerable private sector investment, support the restructuring of vital supply chains, and bolster our exports. The Canada Growth Fund will also provide backing to reduce our emissions and invest in the growth of low-carbon industries.

Climate

Budget 2022 continues to confirm the government’s commitment to fighting climate change. It commits $1.7 billion over five years to extend the Incentives for Zero-Emission Vehicles Program until March 2025 and also provides funding to create a national network of electric vehicle charging stations.

Budget 2022 also commits $250 million over four years to support the development of clean electricity, including inter-provincial electricity transmission projects and Small Modular Reactors.

Bank And Insurer Taxes

Budget 2022 introduced a new financial measure called the Canada Recovery Dividend. Banks and insurers will have to pay a one-time, 15% tax on 2021 taxable income above $1 billion. This tax will be payable over five years.

Budget 2022 also proposes increasing the tax rate on income above $100 million for banks and insurers to 16.5% (currently 15% for other corporations).

Wondering How This May Impact You?

If you have any questions or concerns about how the new federal budget may impact you, call us – we’d be happy to help you!

https://aquafinancialconsulting.com/wp-content/uploads/2022/04/federalBudget2022FI.jpeg 281 500 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2022-04-08 12:48:392022-04-08 13:28:142022 Federal Budget Highlights
Page 1 of 212

Search Blog Posts

Search Search

Latest News

  • The Benefits of Working With An Employee Benefits SpecialistSeptember 2, 2026 - 4:10 pm
  • Choosing A Group Benefits ProviderAugust 8, 2026 - 1:35 am
  • Financial Checklist for New Parents in CanadaJune 30, 2026 - 4:13 pm

Categories

  • 2019 Only
  • 2020
  • 2020 Only
  • 2021
  • 2022
  • 2022 Only
  • 2023
  • 2024
  • 2025
  • 2026
  • Accountants
  • Archive
  • Blog
  • Business owners
  • Buy Sell
  • Center of Influences
  • Charitable Gifting
  • Coronavirus
  • Coronavirus – associates
  • Coronavirus – practice Owners
  • Coronavirus – Retired
  • Coronavirus – Retiring
  • Coronavirus -students
  • Corporate
  • critical illness insurance
  • Debt
  • dental benefits
  • Disability
  • disability insurance
  • Estate planning
  • Family
  • farmers
  • financial advice
  • financial planning
  • Government Budget
  • group benefits
  • Health benefits
  • incorporated professionals
  • Individuals
  • Insurance
  • Investment
  • Life insurance
  • long term care
  • mortgage
  • Pension plan
  • personal finances
  • Professional Corporations
  • Professionals
  • RDSP
  • Registered Education Savings Plan
  • Retirees
  • Retirement
  • RRSP
  • Tax
  • Tax free savings account
  • travel insurance

Get in Touch

Aquafinancial Consulting
Walé Gbalajobi, BA, FICB, PFP
Financial Advisor
T: (403) 804-4486
aquafina@aquafinancialconsulting.com

3402 8 Street SE
Calgary, AB
T2G 5S7

Book an appointment for an online preliminary online meeting

Latest News

  • The Benefits of Working With An Employee Benefits SpecialistSeptember 2, 2026 - 4:10 pm
  • Choosing A Group Benefits ProviderAugust 8, 2026 - 1:35 am
  • Financial Checklist for New Parents in CanadaJune 30, 2026 - 4:13 pm

About

We tailor all our financial consulting services to suit the needs of individual clients. We assign a team of dedicated personnel to work with every client. Our experienced personnel have years of experience in financial consulting making us ideal for all individual and small business financial consulting needs.

Sign up for our newsletter

* indicates required
©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
  • Link to LinkedIn
  • Link to Facebook
  • Link to X
Scroll to top Scroll to top Scroll to top