Aquafinancial Consulting
  • HOME
  • SERVICES
    • INDIVIDUALS & FAMILIES
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING FOR YOUNG FAMILIES
      • ESTATE PLANNING FOR RETIREES & MATURE FAMILIES
      • INSURANCE PLANNING
    • BUSINESS OWNERS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
      • ESTATE PLANNING
      • SUCCESSION PLANNING
      • INSURANCE PLANNING
    • INCORPORATED PROFESSIONALS
      • FINANCIAL ADVICE
      • RETIREMENT PLANNING
    • INSURANCE
      • DISABILITY
      • CRITICAL ILLNESS
      • LIFE
        • PERSONAL
        • CORPORATE
      • HEALTH & DENTAL
      • FOR YOUNG FAMILIES
      • FOR BUSINESS OWNERS
    • INVESTMENT
      • REGISTERED EDUCATION SAVINGS PLAN
      • TAX FREE SAVINGS ACCOUNT
      • REGISTERED RETIREMENT SAVINGS PLAN
      • REGISTERED RETIREMENT INCOME FUND
      • ANNUITIES
    • GROUP BENEFITS
      • HEALTH BENEFITS
      • RETIREMENT BENEFITS
  • ABOUT
    • ABOUT
    • SUPPLIERS
    • PRIVACY & WEBSITE TERMS OF USE
  • NEWS
  • EVENTS
  • CONTACT
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to LinkedIn
  • Link to Facebook
  • Link to X

Archive for category: Coronavirus – Retired

Personal Tax Planning Tips – End of 2020 Tax Year
December 2, 2020/in 2020 Only, Blog, Charitable Gifting, Coronavirus, Coronavirus - associates, Coronavirus - practice Owners, Coronavirus - Retired, Coronavirus - Retiring, Coronavirus -students, Disability, disability insurance, Family, financial advice, financial planning, Health benefits, Pension plan, RDSP, Registered Education Savings Plan, RRSP, Tax, Tax free savings account/by Aquafinancial Consulting

Now that we are reaching the end of the tax year, it’s an excellent time to review your finances. We’ve listed below some of the critical areas to consider and provide you with useful guidelines.

We have divided our tax planning tips into five sections:

  • Tax Deadlines

  • Individual tax issues

  • Family tax issues

  • Managing your investments

  • Retirement planning

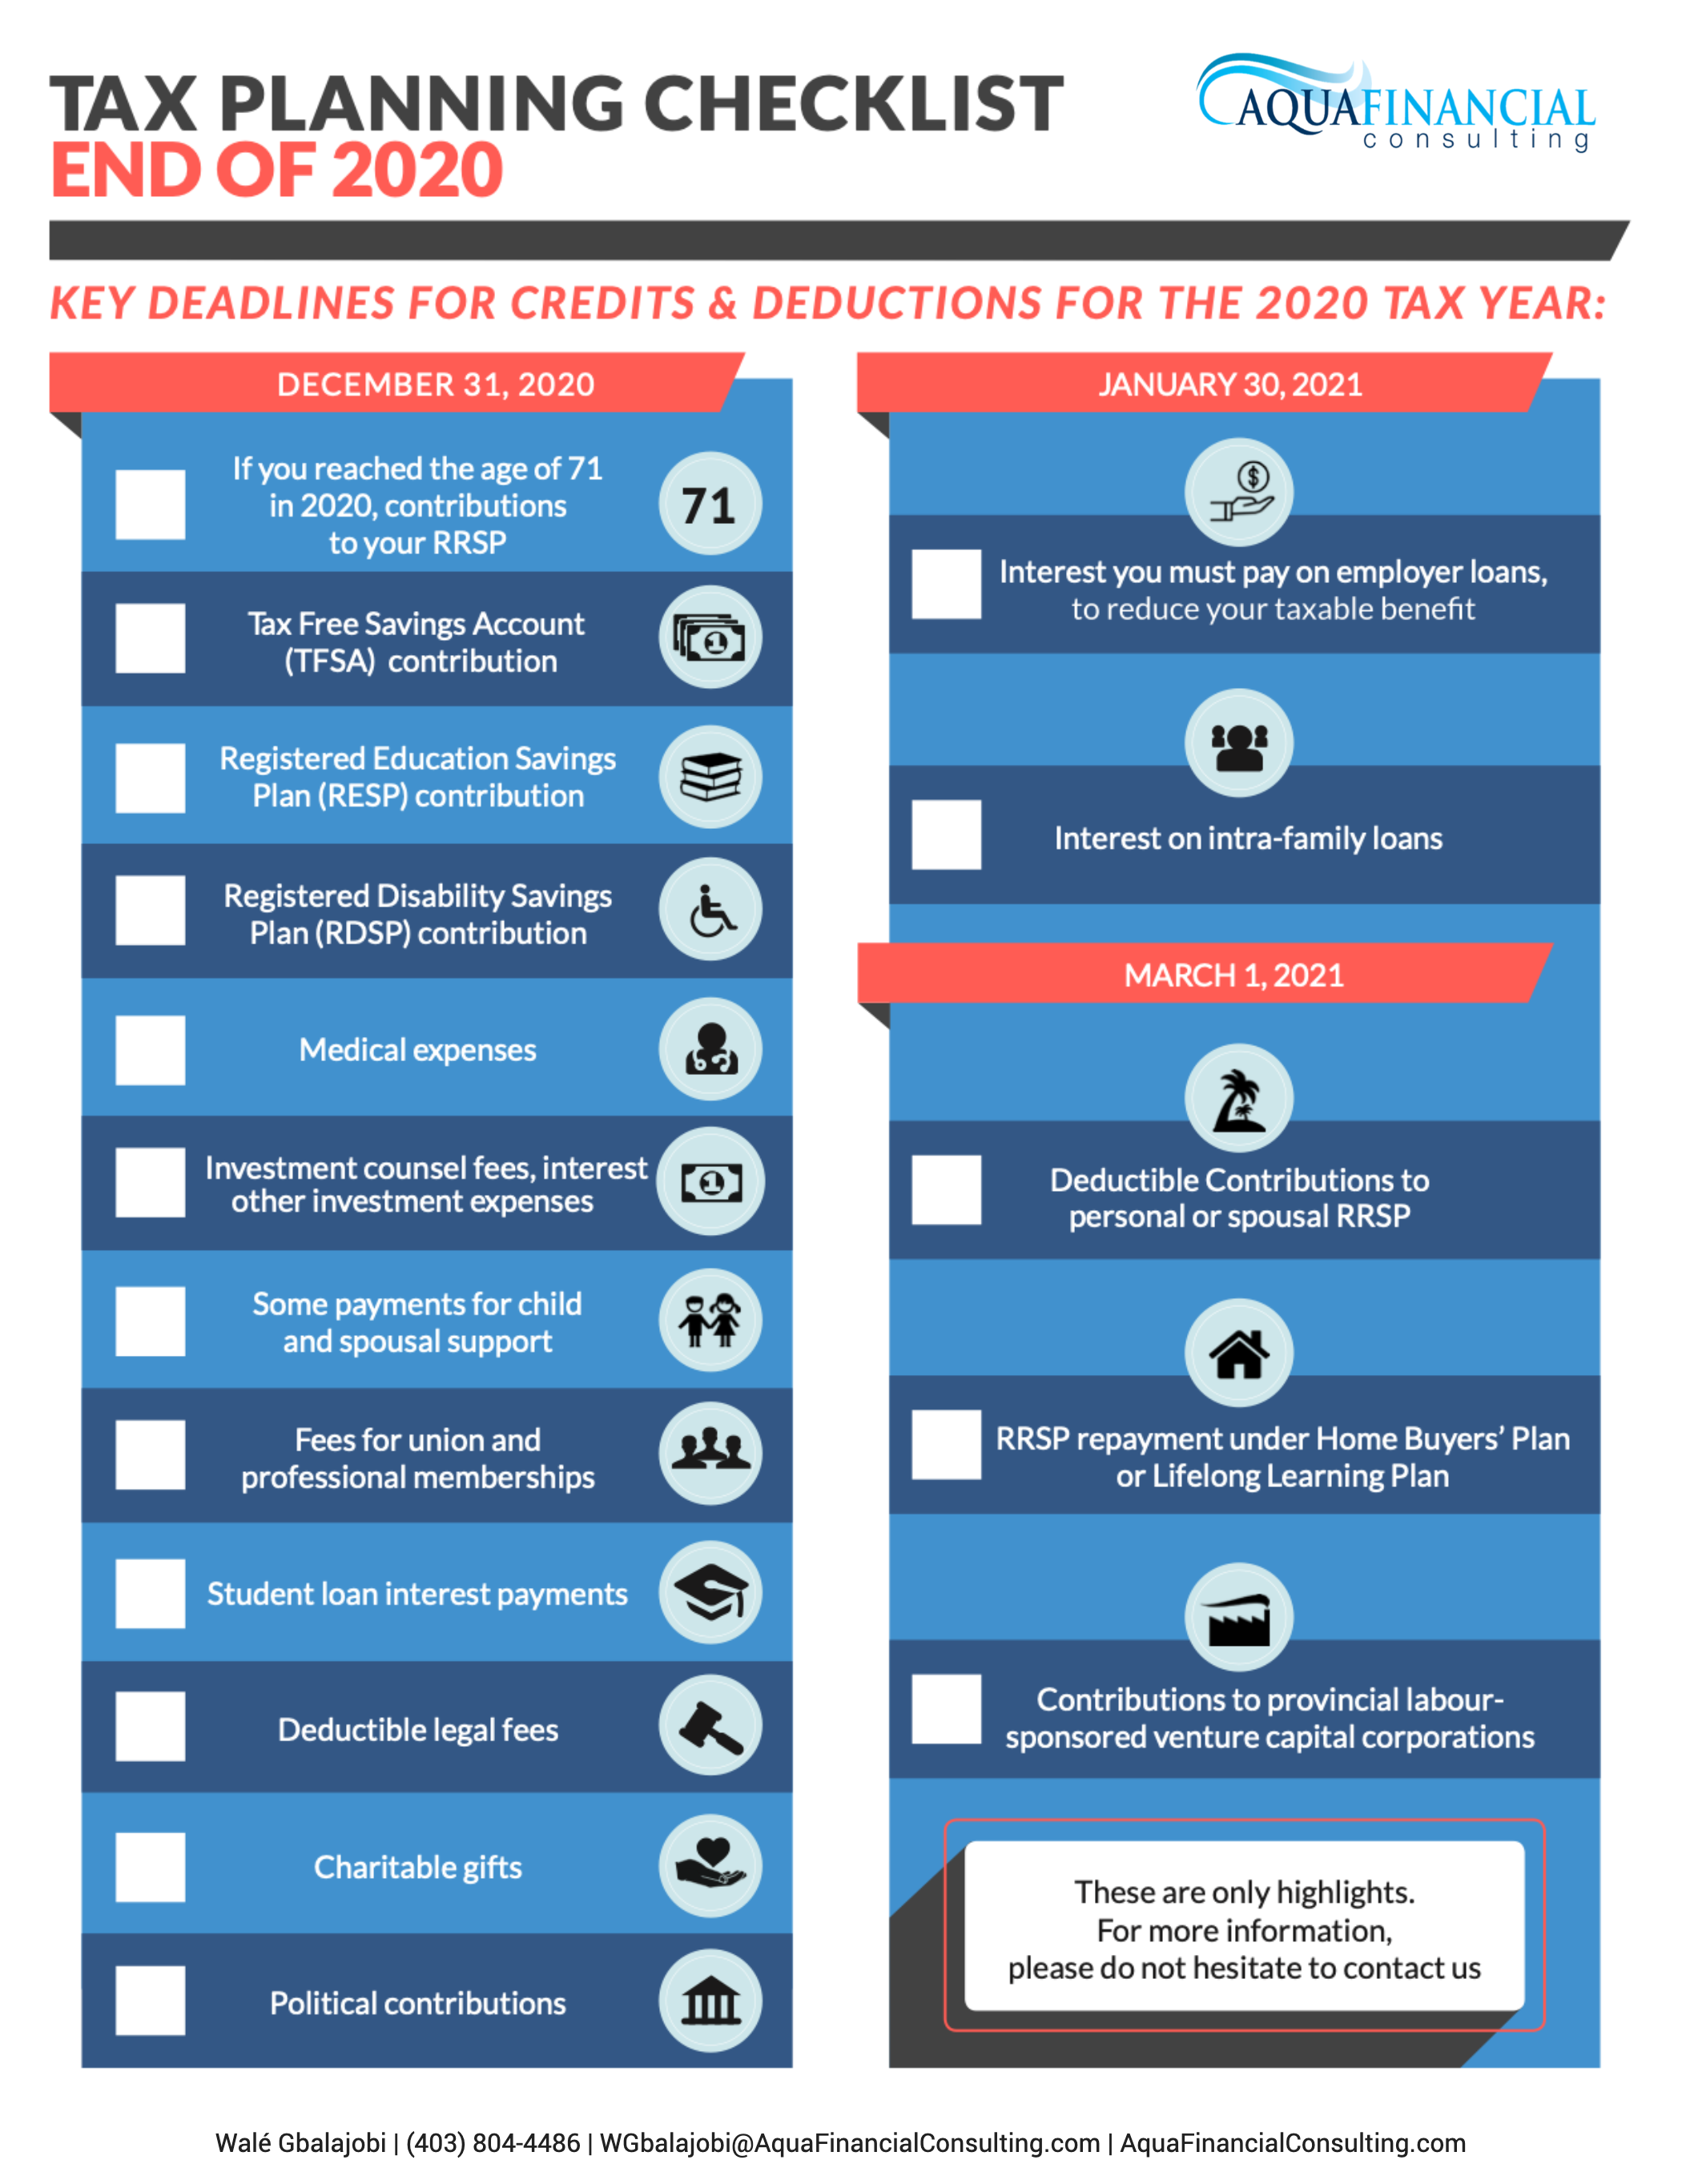
Tax Deadlines for 2020 Savings

December 31, 2020:

  • If you reached the age of 71 in 2020, you can’t contribute to your RRSP after this date

  • Use up your TFSA contribution room

  • Contribute to an RESP to get the Canadian Education Savings Grant (CESG) and the income-tested Canada Learning Bond (if eligible).

  • Contribute to an RDSP to get the Canada Disability Savings Grant (CDSG) and the income-tested Canada Disability Savings Bond (if eligible).

  • Medical expenses

  • Investment counsel fees, interest and other expenses relating to investments

  • Some payments for child and spousal support

  • Fees for union and professional memberships

  • Student loan interest payments

  • Deductible legal fees

  • Charitable gifts

  • Political contributions

January 30, 2021

  • Interest on intra-family loans

  • The interest you must pay on employer loans to reduce your taxable benefit

March 1, 2021

  • Contributions to provincial labour-sponsored venture capital corporations

  • RRSP Repayment under Home Buyers Plan or Lifelong Learning Plan

  • Deductible contributions to a personal or spousal RRSP

Individual Tax Issues

To help Canadians deal with financial hardships due to job loss because of COVID-19, the Canadian government introduced several benefit programs. If you received any of these benefits, you should be aware of the tax ramifications.

The Canada Emergency Response Benefit (CERB) was the first benefit program issued by the government and ran until September 26, 2020. If you received the CERB at all during 2020, the government will issue you at T4A, showing how much money you received from the CERB program. You must then declare that as income when filing your 2020 income tax return. Since no tax was taken off at the source, be sure to put aside money to pay for potential income taxes on your CERB income.

As of September 27, 2020, the government offered three replacement benefit programs:

  • Canada Recovery Benefit (CRB)
    This is for people impacted by COVID-19 who work but are not eligible for EI (e.g. self-employed).

  • Canada Recovery Sickness Benefit (CRSB)
    This is for people who are employed cannot work due to COVID-19 and do not have access to paid sick leave.

  • Canada Recovery Caregiving Benefit (CRCB)
    This is for people who must miss work to care for a family member who has COVID-19.

For all three of these programs, the government will be withholding 10% in taxes upfront, but you may end up owing extra tax, depending on the rest of your income for 2020, so it’s important to set extra money aside for taxes.

Also, there is a unique condition for the CRB only. If you make over $38,000 in 2020 (excluding the CRB), you will have to pay back the CRB at a rate of 50 cents for each dollar of CRB you earned above the threshold.

If you paid interest on an eligible student loan in 2020, you can claim a non-refundable tax credit in the amount of interest you paid by December 31. In addition, you should be aware that student loan payments were frozen for six months – from March 30 to September 30. No interest accrued on student loans during that period.

Family Tax Issues

  • Check your eligibility for the Canada Child Benefit
    (CCB)
    To receive the Canada Child Benefit in 2021/22, you need to file your tax returns for 2020 as the benefit is calculated using your family income from the previous year. Eligibility for the CCB depends on set criteria such as your family’s income, how many children you have, and how old they are. You may qualify for a full or partial amount, depending on whether you have full custody or shared custody.

  • Consider family income splitting

    The CRA offers a prescribed low-interest rate on family loans. Therefore, it makes sense to consider setting up an income splitting loan arrangement with your family members. If you do this, you can potentially lock in a family loan at a low-interest rate of 1% and then invest the borrowed money into a higher return investment while benefitting from your family member’s lower tax status. Don’t forget to adhere to the Tax on Split Income rules.

Managing Your Investments

  • Use up your TFSA contribution room

    If you can, it’s worth contributing the full $6,000 to your TFSA for 2020. You can also contribute more (up to $69,500) if you are 29 or older and haven’t made any previous TFSA contributions.

  • Contribute to a Registered Education Savings Plan (RESP)

    The Registered Education Savings Plan (RESP) is a savings plan for parents and others to save for a child’s education. The Canada Education Savings Grant (CESG) will match up to 20% of your contributions up to a maximum of $2,500.

    That means the CESG can add a maximum of $500 to an RESP each year. The grant room accumulates until your child turns 17. Therefore, any unused CESG amounts for the current year are automatically carried forward for possible use in the future years.

    The income-tested Canada Learning Bond (CLB) is paid directly to a child’s RESP by the Canadian government to low-income families. No personal contributions are required to receive the CLB.

  • Contribute to a Registered Disability Savings Plan (RDSP)

    The Registered Disability Savings Plan (RDSP) is a savings plan for parents and others to save for the financial security of a person who is eligible for the Disability Tax Credit (DTC). The government will pay a matching Canada Disability Savings Grant (CDSG) up to 300% – depending on the beneficiary’s adjusted family net income and amount contributed.

    Also, low-income Canadians with disabilities may be eligible for a Canada Disability Savings Bond (CDSB). If you qualify, it will be paid directly to your RDSP.

    The government will pay matching grants or bonds into the RSDP up to and including the end of the year the recipient turns 49. Be aware that there is a 10-year carry-forward of CDSG and CDSB entitlements.

  • Donate securities to charity

    Donating by year-end will provide you with tax savings. If you donate eligible securities or mutual funds, capital gains tax does not apply, and you can receive a tax receipt for their full market value. Also, the charity gets the full value of the securities.

  • Think about selling any investments with unrealized capital losses

    It might be worth doing this before year-end to apply the loss against any net capital gains achieved during the last three years. The last trading date for 2020 for Canadian and US publicly traded stocks will be Tuesday December 29th in order to record the gain or loss in the 2020 taxation year.

    Conversely, if you have investments with unrealized capital gains that cannot be offset with capital losses, it may be worth selling them after 2020 to be taxed on the income the following year.

  • Consider the timing of purchasing of certain non-registered investments

    Suppose you are considering purchasing an interest-bearing investment like a guaranteed investment certificate (GIC) with a maturity date of one year or more. In that case, you may consider delaying the purchase to the following year, so you don’t have to pay tax on accrued interest until 2021. You should also consider this with mutual funds that make taxable distributions before the end of 2020, consider delaying this until early 2021. Don’t pay taxes earlier than necessary.

  • Check if you have investments in a corporation

    The new passive investment income rules apply to tax years from 2018 onwards. They state that the small business deduction is reduced for companies with between $50,000 and $150,000 of investment income. Therefore, the small business deduction has entirely stopped for corporations that earn a passive investment income of more than $150,000.

    Note – At a provincial level, both Ontario and New Brunswick do not follow the federal rules to limit access to the small business deduction.

Retirement Planning

  • Make the most of your RRSP

    The deadline for making contributions to your RRSP for the year 2020 is March 1, 2021. The deduction limit for 2020 is limited to 18% of the income you earned in 2020, to a maximum of $27,230. This maximum amount is impacted by the following:

  1. Any pension adjustment

  2. Any previous unused RRSP contribution room

  3. Any pension adjustment reversal.

Remember that deducting your RRSP contribution reduces your after-tax cost of making said contribution.

  • Check when your RRSP is due to end

    If you reach the age of 71 during 2020, you must wind up your RRSP this year. You must make your final contribution to it by December 31, 2020.

  • Convert to RRIF before year-end

    If you turned 65 during 2020 or are already older than 65, you’re entitled to a pension credit that can fully or partly offset the tax on the first $2,000 of eligible income annually. Consider setting up an RRIF before year-end to pay out $2,000 annually if you don’t have any other eligible pension income.

If you have any questions about your taxes for 2020, contact us – we can help you!

https://aquafinancialconsulting.com/wp-content/uploads/2020/12/Personal-tax-planning-tips-2020@1000px.png 563 1000 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2020-12-02 14:07:542020-12-02 15:09:24Personal Tax Planning Tips – End of 2020 Tax Year

CERB transitions to NEW Recovery Benefits and EI

August 21, 2020/in 2020, Blog, Coronavirus, Coronavirus - associates, Coronavirus - practice Owners, Coronavirus - Retired, Coronavirus - Retiring, Coronavirus -students/by Aquafinancial Consulting

CERB extended by 4 weeks

On August 20th, the Federal Government announced the extension of the Canada Emergency Response Benefit (CERB) by one month and the subsequent transition, on September 27th, to a simplified Employment Insurance (EI) Program for those who remain unable to work and are eligible.

Temporary revised EI benefit qualifications:

  • 120 hours of work required to qualify

  • Minimum benefit rate of $400 per week

  • At least 26 weeks of regular benefits

Canada Recovery Benefit

Effective September 27th, 2020 for 1 year, the Canada Recovery Benefit will provide $400 / week for up to 26 weeks for those who are not eligible for EI, like self-employed and gig economy workers.

Eligibility from canada.ca:

“The benefit would be available to residents in Canada who:

  • are at least 15 years old and have a valid Social Insurance Number (SIN);

  • have stopped working due to the COVID-19 pandemic and are available and looking for work; or are working and have had a reduction in their employment/self-employment income for reasons related to COVID-19;

  • are not eligible for Employment Insurance;

  • had employment and/or self-employment income of at least $5,000 in 2019 or in 2020; and,

  • have not quit their job voluntarily.

Workers would apply after every two-week period for which they are seeking income support and attest that they continue to meet the requirements. In order to continue to be eligible for the benefit the claimant wound need to look for and accept work when it is reasonable to do so. The benefit is taxable.”

Canada Recovery Sickness Benefit

Effective September 27th, 2020 for 1 year, the new Canada Recovery Sickness Benefit will provide $500 / week for up to 2 weeks for workers who are unable to work because they are sick or must isolate due to COVID-19.

Eligibility from canada.ca:

“The benefit would be available to:

  • Residents in Canada who are at least 15 years of age and have a valid Social Insurance Number (SIN);

  • Workers employed or self-employed at the time of the application; and

  • Workers who earned at least $5,000 in 2019 or in 2020.

Workers would not be required to have a medical certificate to qualify for the benefit. Workers could not claim the Canada Recovery Sickness Benefit and receive other paid sick leave for the same benefit period. Workers would need to have missed a minimum of 60% of their scheduled work in the week for which they claim the benefit.

Workers would apply after the one-week period in which they are seeking income support and attest that they meet the requirements. The benefit would taxable.”

Canada Recovery Caregiving Benefit

Effective September 27th, 2020 for 1 year, the new Canada Recovery Caregiver Benefit will provide $500 / week for up to 26 weeks per household to eligible Canadians.

The news release from canada.ca, states that:

“The closure of schools and other daycare and day program facilities to prevent the spread of COVID 19 has meant that many Canadians have been unable to work because they needed to provide care to children or support to other dependents who had to stay home. While it is anticipated that facilities will gradually re-open as the economy restarts, the Government of Canada recognizes that access may vary over time and across communities. The Government is committed to ensuring that parents and others with dependents do not need to choose between caring for them and paying the bills.”

Eligibility from canada.ca:

In order to be eligible for the Canada Recovery Caregiving Benefit, individuals would need to:

  • reside in Canada;

  • be at least 15 years of age on the first day of the period for which they apply for the benefit;

  • have a valid Social Insurance Number;

  • be employed or self-employed on the day immediately preceding the period for which the application is made;

  • have earned at least $5,000 in 2019 or in 2020;

  • have been unable to work for at least 60% of their normally scheduled work within a given week because of one of the following conditions:

    • they must take care of a child who is under 12 years of age on the first day of the period for which the benefit is claimed:

      • because their school or daycare is closed or operates under an alternative schedule for reasons related to the COVID-19 pandemic;

      • who cannot attend school or daycare under the advice of a medical professional due to being at high risk if they contract COVID-19; or

      • because the caregiver who usually provides care is not available for reasons related to the COVID-19 pandemic; or

    • they must provide care to a family member with a disability or a dependent:

      • because their day program or care facility is closed or operates under an alternative schedule for reasons related to COVID-19;

      • who cannot attend their day program or care facility under the advice of a medical professional due to being at high risk if they contract COVID-19; or

      • because the caregiver who usually provides care is not available for reasons related to the COVID-19 pandemic;

  • not be in receipt of paid leave from an employer in respect of the same week; and

  • not be in receipt of the CERB, the EI Emergency Response Benefit (ERB), the Canada Recovery Benefit, the Canada Recovery Sickness Benefit, short-term disability benefits, workers’ compensation benefits, or any EI benefits or Quebec Parental Insurance Plan (QPIP) benefits in respect of the same week.

Workers would apply after the period in which they are seeking income support and attest that they meet the requirements. Two members residing in the same household could not be in receipt of the benefit for the same period. The benefit is taxable.

CLICK TO VIEW FULL DETAILS
https://aquafinancialconsulting.com/wp-content/uploads/2020/08/CERB_to_Recovery_Benefits@2x.png 640 1000 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2020-08-21 14:25:122020-08-21 15:54:12CERB transitions to NEW Recovery Benefits and EI

Apply starting Friday for Canada Emergency Student Benefit! Help on the way for seniors.

May 13, 2020/in 2020 Only, Blog, Coronavirus, Coronavirus - Retired, Coronavirus -students, Retirement/by Aquafinancial Consulting

Students can apply for $1,250 through the Canada Emergency Student Benefit starting Friday

From canada.ca:

“The Canada Emergency Student Benefit (CESB) provides financial support to post-secondary students, and recent post-secondary and high school graduates who are unable to find work due to COVID-19.

This benefit is for students who do not qualify for the Canada Emergency Response Benefit (CERB) or Employment Insurance (EI).

From May to August 2020, the CESB provides a payment to eligible students of:

  • $1,250 for each 4-week period

  • $2,000 for each 4 -week period, if you have dependants or a disability”

Learn More and Apply for CESB

Seniors to receive up to $500 one-time payment

The Government of Canada will be providing help to vulnerable seniors by providing a one-time tax-free payment of $300 for seniors eligible for Old Age Security (OAS). For seniors eligible for the Guaranteed Income Supplement (GIS), they will receive an additional $200.

Learn More about Help for Seniors
https://aquafinancialconsulting.com/wp-content/uploads/2020/05/CESB_Starts_Friday@2x.png 640 1000 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2020-05-13 13:51:172020-05-13 15:21:07Apply starting Friday for Canada Emergency Student Benefit! Help on the way for seniors.

Guide to Covid-19: Government Relief Programs in Canada

May 4, 2020/in 2020, Blog, Coronavirus, Coronavirus - associates, Coronavirus - practice Owners, Coronavirus - Retired, Coronavirus - Retiring, Coronavirus -students, Family, Individuals, Life insurance/by Aquafinancial Consulting

The intention for our “Guide to Covid-19: Government Relief Programs in Canada” is to help businesses and individuals to cut through the noise and make sure they’re getting all the help they can receive from the federal and provincial programs.

Federal programs include:

  • Small Business Wage Subsidy

  • Canada Emergency Wage Subsidy

  • Canada Emergency Business Account

  • Canada Emergency Response Benefit

  • Student Loan Programs

Individual provincial programs include:

  • Utilities

  • Housing

  • Student Loan Programs

Download the Guide
https://aquafinancialconsulting.com/wp-content/uploads/2020/05/covidGuideCanadaAdvisor_Page_01-scaled.jpg 2560 1810 Aquafinancial Consulting https://aquafinancialconsulting.com/wp-content/uploads/2020/04/aqua-logo-revised@2x.png Aquafinancial Consulting2020-05-04 12:16:202020-05-04 13:00:16Guide to Covid-19: Government Relief Programs in Canada

Search Blog Posts

Search Search

Latest News

  • Succession Planning for Business OwnersOctober 6, 2026 - 11:00 am
  • The Benefits of Working With An Employee Benefits SpecialistSeptember 2, 2026 - 4:10 pm
  • Choosing A Group Benefits ProviderAugust 8, 2026 - 1:35 am

Categories

  • 2019 Only
  • 2020
  • 2020 Only
  • 2021
  • 2022
  • 2022 Only
  • 2023
  • 2024
  • 2025
  • 2026
  • Accountants
  • Archive
  • Blog
  • Business owners
  • Buy Sell
  • Center of Influences
  • Charitable Gifting
  • Coronavirus
  • Coronavirus – associates
  • Coronavirus – practice Owners
  • Coronavirus – Retired
  • Coronavirus – Retiring
  • Coronavirus -students
  • Corporate
  • critical illness insurance
  • Debt
  • dental benefits
  • Disability
  • disability insurance
  • Estate planning
  • Family
  • farmers
  • financial advice
  • financial planning
  • Government Budget
  • group benefits
  • Health benefits
  • incorporated professionals
  • Individuals
  • Insurance
  • Investment
  • Life insurance
  • long term care
  • mortgage
  • Pension plan
  • personal finances
  • Professional Corporations
  • Professionals
  • RDSP
  • Registered Education Savings Plan
  • Retirees
  • Retirement
  • RRSP
  • Tax
  • Tax free savings account
  • travel insurance

Get in Touch

Aquafinancial Consulting
Walé Gbalajobi, BA, FICB, PFP
Financial Advisor
T: (403) 804-4486
aquafina@aquafinancialconsulting.com

3402 8 Street SE
Calgary, AB
T2G 5S7

Book an appointment for an online preliminary online meeting

Latest News

  • Succession Planning for Business OwnersOctober 6, 2026 - 11:00 am
  • The Benefits of Working With An Employee Benefits SpecialistSeptember 2, 2026 - 4:10 pm
  • Choosing A Group Benefits ProviderAugust 8, 2026 - 1:35 am

About

We tailor all our financial consulting services to suit the needs of individual clients. We assign a team of dedicated personnel to work with every client. Our experienced personnel have years of experience in financial consulting making us ideal for all individual and small business financial consulting needs.

Sign up for our newsletter

* indicates required
©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
  • Link to LinkedIn
  • Link to Facebook
  • Link to X
Scroll to top Scroll to top Scroll to top